


More money sits under women's direction every year. By 2030, women are projected to hold roughly 70% of personal wealth in the United States, up from more than half today. The giving research is a preview of what a good share of that will go toward. The data is fascinating, and I think there’s something important to be learned from women’s growing role in financial decision-making.
The Data on Women’s Philanthropy
The Women's Philanthropy Institute at Indiana University's Lilly Family School of Philanthropy has studied gender and giving since 2010. A few findings have held up across the series.
Women are more likely to give. Their first major report found women as much as 40% more likely to donate than men, and women across nearly every income category gave significantly more than comparable men, often close to twice as much. (TimeCSRWire)
This is not only about wealthy women. Comparing male- and female-headed households by income group showed that women at nearly every level gave more, and were more likely to give, than men of similar income and circumstances. (Indiana University)
Women spread their giving out. Women tend to give across more organizations, while men concentrate their giving, and women are more likely to give to almost every charitable subsector. (Causes Women Support)
It held through a crisis. Across twenty years of data through 2020, the long decline in household giving started later and was less pronounced for single women than for single men. (Women Give 2024)
The motivation research is what stopped me. Empathy correlates with charitable giving, and it is a very strong motivation for women, while men's giving more often runs on other motivations.
That matches what I see. The women I work with who give the most are not giving for the deduction. They have been connected to the same organizations for decades; they know the people running them, and they feel pulled to help.
Several of them give away their entire required minimum distribution through a qualified charitable distribution once they reach 70½, sending the money straight from the IRA to the organization without paying tax on it along the way.
My mother is one of these women. She has been generous my whole life, and I did not understand until much later how much it shaped the way I think about money.
(This Is NOT a Knock on Men)
I have male clients who are extraordinarily generous, and this research describes averages, not individuals. What interests me is what follows. If women are consistently doing something well, there are two questions the rest of us should be asking.
How to Give Well
Giving decisions get made in December, alone, under a deadline, with a tax number in hand. That is the worst possible setting for a decision that is supposed to mean something.
A few things that make the conversation better:
Both of you name causes first, dollars second. Numbers end conversations. Reasons start them.
Say why it matters to you. The story behind an organization is usually the part your spouse has never heard.
Expect your lists to differ and treat that as information. Two different lists mean the household cares about more than it realized.
Fund some of each. You don't have to fully agree, but you can compromise and make space for both people's passion areas.
Put it on the calendar twice a year. Once to decide, once to look back at what it did.
Giving From Connection
In my experience, the giving that lasts is the giving both people can explain. It survives a bad market, because the reason did not change. It gives children something to take part in rather than inherit. It usually points to the same few organizations for years.
Once you know what you are funding and why, the tax work is our job. There is almost always a better route than writing a check, whether that is appreciated stock, a donor-advised fund, or a qualified charitable distribution from an IRA once you reach 70½. Those tools matter. They work best when they are carrying a decision you already made together.
If you have wanted to be more generous or facilitate more conversations around family giving, try out the bullet points above. I think you'll find giving can be one of the most enjoyable uses of your wealth when healthy dialogue drives it.
One of the primary things we do at Financial House is help families, and especially women among my clients, reach a sense of financial clarity and organization if you want more confidence that you know where you are in your journey to and through retirement. Our team covers six areas that create comprehensive financial plans.
Investments
Insurance
Tax planning
Estate planning
Giving and legacy
Income and cash flow
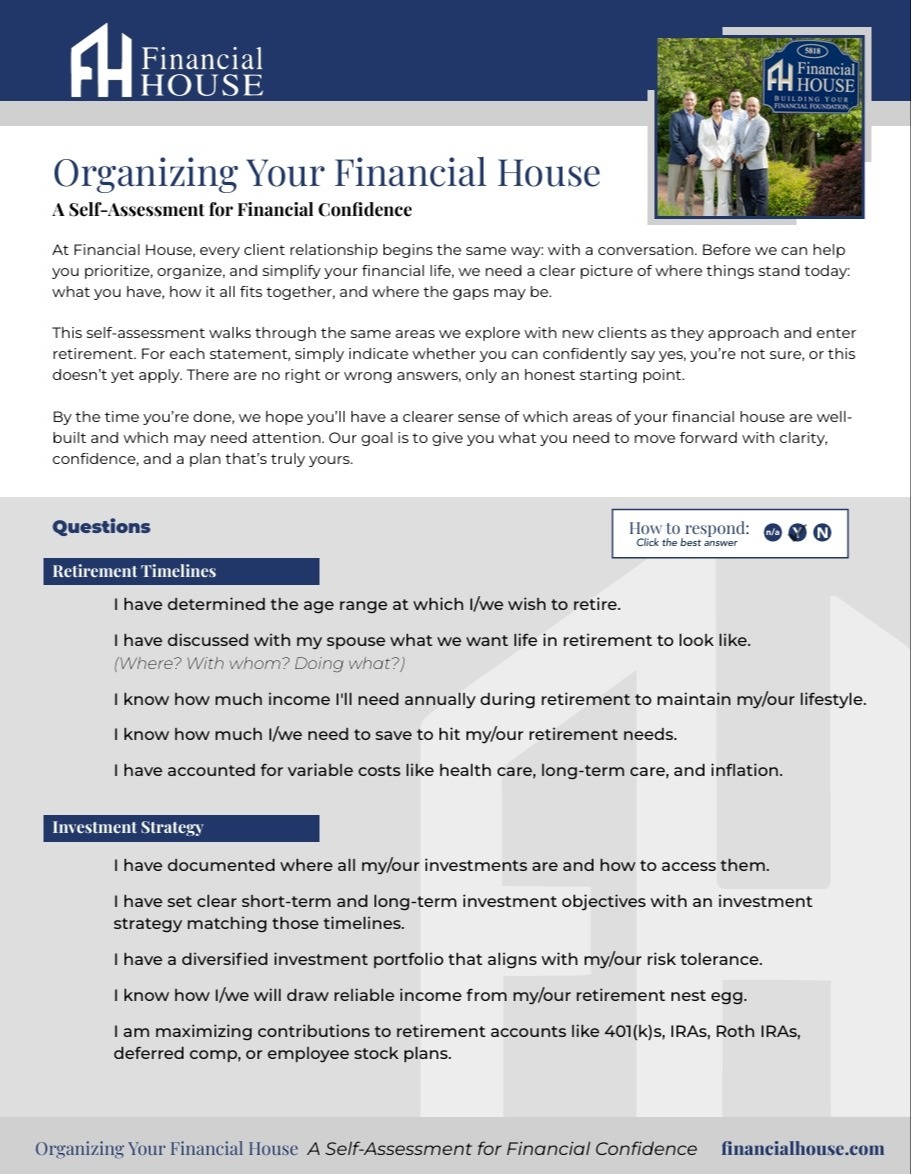
If you have clarity in these six areas, you can feel much more confident going into retirement. If you're wondering how you are doing, our team put together a self-assessment that helps you identify the areas where you need to find answers to key questions. You can take a look at it here.
Download the Confidence Assessment
Securities and Advisory services offered through LPL Financial, a Registered Investment Advisor. Member FINRA & SIPC.
The LPL Financial representatives associated with this website may discuss and/or transact securities business only with residents of the following states: AK, AZ, CA, CO, CT, DE, DC, FL, GA, HI, IL, IN, KY, ME, MD, MA, MI, MT, NV, NJ, NM, NY, NC, OH, PA, RI, SC, TN, TX, VT, VA, & WA
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.